Friday, July 20, 2007

Sub-Prime Mortgage Mess: Did It take a genius?

I'm often amazed at how really smart people can get caught up in the crowd, along with their friends and peers. Caught up in the Extraordinary Popular Delusions and Madness of Crowds, even really smart people have trouble rationalizing their behaviours later, in a way that doesn't sound like they themselves still haven't figured out what happened to them.

In this category then, perhaps I should apply for a job as the head of GE, or perhaps GE Capital, or perhaps as the GE Chief Financial Officer (CFO). GE has recently decided to exit the sub-prime mortgage business, due to its obvious problems and potential for more. In reading one account of the reason they were exiting, GE CFO Keith Sherin said this ...

"In the first quarter we said we were committed to the business and we were. Based on the changes we saw, we made the decision to exit the business. I think it was a smart move."

Note: If you're on a blog aggregator, you can visit The Confused Capitalist here (or here: http://confusedcapitalist.blogspot.com/) for additional articles and exclusive content!

Back in March 2006 (just after this blog started), I posted on the housing market and the potential for sub-prime loans to wreck havoc on the bottom line, suggesting that ...


"Having seen the tall-headed gnomes in my own financial field previously lend to extreme ratios in the dying days of a real estate upswing, I thought they'd have figured out that lending like that at the end of a long cycle, isn't very good for the bottom line. "

I guess if Keith Sherin didn't realize it wasn't a very good business to be in at the top of a real estate cycle (like about a year-and-half earlier, when they could have sold these assets for a lot more money, instead of taking a charge to get out of the business), then I'm a lot wiser than he is.
Hmmm, I wonder what the pay is in his job? Mr. Immelt let's talk stock options ... how many can I get?


JW

The Confused Capitalist

Saturday, July 07, 2007

Two worthy newcomers to the financial bloggers world ...

There's two new blogs out there that I'd like to draw your attention to. Two blogs that might battle for your attention in the future.

The first is a blog written by a TOC, Deborah, from near my area, in rainy Vancouver, BC. She writes a blog called Making Sense of My World.

It's an exceptionally detailed look into the world of mining stocks, primarily, but she occasionally touches on other financial subjects as well. It's clear to any reader, including one like myself who has little understanding of mining stocks, that she has dived in deep enough to figure out "What's Up".

With her, "making sense of my [her] world", she's helped me understand the mining world a bit more. I highly recommend a visit to "Deb's World". See also the new link on my blogroll.

Note: If you're on a blog aggregator, you can visit The Confused Capitalist here for additional articles and exclusive content!

The second blog I'd like to draw your attention to is one written by Eric Fox, the Market Prognosticator. Eric recently emailed me and asked me if I'd take a look around his blog. I like someone who asks for what they want, and Eric did that. I was very pleasantly surprised when I read several of his articles, and liked his edgy tone and slant on things. I read several of the articles and enjoyed them thoroughly. An excerpt from ... The Most Terrifying Thing I Have Read in My Life ...


I get an e-mail every morning with a recap of what is going in the market. Most of the time the articles are something I have read somewhere else or I am not interested in them. Today was different. The headline was enticing. It read: How do you pay off your home mortgage in a few years or less? Learn to use hedged ...

The last word was left off but it was not rocket science to guess that the missing word was "futures." Oh this was going to be fun. When I clicked on the link it was even better than I thought. It read: How do you pay off your home mortgage in a few years or less? Learn to use hedged futures with options and arbitrageur strategy.

Well sure why not? There's nothing wrong with 80 million homeowners entering the futures market. This might even solve the sub prime lending mess. People who can't even read a mortgage note trading futures and options.


Eric goes on in the article ... rather amusingly, I might add. I recommend his blog for those looking for a bit of insight and spicy writing.

Find also the link to Eric's blog in my blog roll to the right. Well, hope you all had a safe and enjoyable Independence Day. Bye for now ...


JW

The Confused Capitalist

Saturday, June 30, 2007

Raising the Median: Computer Hardware and Software

Image Source: MadAsHellClub.Net

I'm mad as hell and not going to take it any more! (Well, not really, but I am more than a bit disturbed [ask anyone who knows me] :-)

In any case, I've kind of had it with computer hardware and software makers who don't promote better ways to do things and perpetuate the mediocre or inferior.

One obvious example of this is the present keyboard you are probably typing on (just as I am). It's antiquated and inferior in two very obvious ways:
  • Firstly, the actual locale of the letters on the QWERTY keyboard layout, is a relatively slow method to type (created to slow typing down, so 18th century typewriters wouldn't jam). Because of this crappy letter layout, Repetitive Strain Injury (RSI) is epidemic among those regularly using keyboards. Additionally, it's a slow way to type, compared to several more modern alternatives, particularly a fairly new one that takes advantage of prior Qwerty training, while minimizing re-training time compared to using a Dvorak keyboard.

  • Secondly, the flat keyboard, with its offset letters, also contributes to RSI, to a higher error rate, and was something that was designed for the actual mechanics of a typewriter, never for the human being. That the computer makers chose to perpetuate this too when manufacturing computer keyboards, is even more unbelievable.

So, in relation to item #1 above, a Dvorak layout (which many of you may have heard about) is far superior to the standard Qwerty layout and results in superior speed (the world's fastest typist used a Dvorak layout), and less RSI. However, the problem is, is that almost every key (33 of them) is recast elsewhere on the board, with many also jumping between hands.

This results in a steep time-consuming learning curve, and many people give up because of this (as I did), even though you can easily reconfigure your keyboard through a software add-on (go to Microsoft, here, if interested). This is probably the reason that the Dvorak never caught on - the very steep learning curve.

No, based on this idea though, others have been at work to recast the keyboard letters, using the lessons of Dvorak, but minimizing extraneous key movement from the Qwerty standard, where gains are minimal. In the case of the Colemak layout (moves only 17 keys, and minimal moved to the "other" hand), this results in, reportedly, much smaller learning curve, with similar speed and ergonomic gains to Dvorak.

It is now the third-most popular English language layout, and is gaining converts every day. More information, including a downloadable program to convert your existing keyboard to this superior letter layout is located at Colemak.com. I hope to download and convert to this layout. I'll report out on this from time to time.

(Note: If you're on a blog aggregator, you can visit The Confused Capitalist here or here [http://confusedcapitalist.blogspot.com] for additional articles and exclusive content!)

Keyboard layout comparisons (click to enlarge any of the below):

QWERTY (The old-fashioned, crappy, standard)


DVORAK (A better keyboard, that never caught on, probably in part due to the learning curve - look how many keys not only shift position, but from one hand to the other).
COLEMAK (With some luck, this will become the defacto standard, particularly with young people. Note how many Qwerty positions are retained, because moving them doesn't create significant improvement and moving them needlessly creates more difficulty in learning a new board layout for old-timers, like me)


So if you're looking to be a faster typist, to alleviate your own RSI, and just generally to make the world a better place, head on over the Colemak.com for a free download to covert your keyboard. OK, that's Rant #1 over. Let's move onto Rant #2.

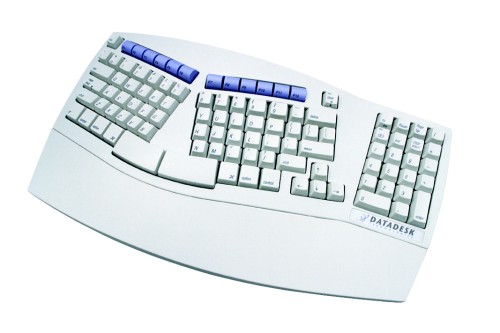
Secondly, the actual keyboard itself sucks! The hardware makers should have corrected the obvious deficiencies in this, once there was no mechanical reason to retain the "offset" configuration. It results in missed keys, too much finger stretching, and incorrect wrist position, among other problems. The Confused Capitalist has been researching this issue however, reading reviews on the net, and believes to have found a superior board.

While some boards split and twist the keyboard (like the Microsoft Ergonomic that I use at work) which solves part of the problem, it still leaves a large portion of the ergonomics unfixed. However, a newer board, called the SmartBoard, solves most of these problems and adds several other key fixes, as well. The SmartBoard is available from datadesktech.com - see image below.
Finally, rant #3, isn't really a rant, but more of an eye opener. Many people use the Microsoft Office programs without believing there's any real alternatives out there. Well, Open Office has been picking up speed lately, and similar in some ways to Linux, converts. It is a free, volunteer-maintained open source program, providing an array of office suite type products. By all accounts on the internet, the latest release is continuing to improve and now rivals most of the Microsoft suite for utility, versatility, sophistication, stability, etc.

In some cases, some of the programs are reported as superior, with the most notable complaints being for the Power Point equivalent "Impress" still not up to the Microsoft standard, while the spreadsheet program "Calc" isn't - for sophisticated users - as good as Excel. However, huge strides have reportedly been made over the prior release. According to my research, many users are reporting that they prefer the Open Office word processor. You can go to OpenOffice.org to download this FREE program. So, even if a couple of the programs aren't quite there yet, it's not hard to think they will be soon.
Oh, and did I mention that Open Office can both properly read and save back into a Microsoft format? So my only question would be - unless you have very sophisticated spreadsheet or presentation needs - why on earth would you spend the bucks to upgrade to the latest Microsoft suite?

By the way, many of you might note the label "Global Warming" below, and wonder how this bloggering possibly ties in with that theme. It's simple really - any improvement in efficiency offers the possibility of turning off the computer sooner, and therefore reduces power consumption. Further, less RSI means fewer trips to the doctor. Ergo, less greenhouse gas emissions.

Secondly, using Open Office, an open source document, means that you don't - perhaps - have to work quite as much, since you don't need to pay for this particular type of product. Ergo, the potential exists for a couple of less trips to work every other year. Times millions of workers = less greenhouse gas emissions.

Perhaps not obvious connections, but ones which can, and I believe, do, exist.

Well, that's it for now - I have all of these links on the right hand side of my blog, under the title "Computer Stuff". I hope you are able to use this to improve your own life - to "raise the median".


JW

The Confused Capitalist

Monday, June 18, 2007

Food Shortages and Food Inflation: Malthusian future?

Image: Food skyscraper of the future?


Although Malthus has long been laughed at by those convinced that technology will solve any problem, in any finite system, one must reach some sort of system limits, as demand for a resource outstrips that method of producing it.

Although it may happen for slightly different reasons than postulated under the Malthusian catastrophe scenario, it appears this is starting to happen with food and will soon be found in a supermarket near you, via food inflation.

There is a confluence of forces that make serious food inflation, at the minimum, particularly likely over the next five to ten years:

Factor number one is the bee die back, and the effect it is likely to have on food prices over the next few years, as yields are curtailed due to a reduction in pollination. One economist figures that this will put over $15 Billion in North American crops at risk, all adding to potential for food inflation.

Factor number two is the growing wealth of emerging markets, and their propensity to emulate a western-style meat-heavy type diet, as wealth grows. This puts increased pressure on grain crops in particular, as it takes anywhere from about 5-20 pounds of grain to produce a single pound of meat. As large populations in China and India move further away from vegetarian or semi-vegetarian type diets, this strains limited global food stores even further, adding to food inflation.

Note: If you're on a blog aggregator, you can visit the Confused Capitalist here or here (http://confusedcapitalist.blogspot.com/) for additional articles and exclusive content!

Factor number three is the changing climate. Scientists have long known that food yields can come under pressure in at least two ways as global temperatures climb. Firstly, at higher temperatures, some plants - despite ample water - either cease production, or lower production. In either case, yields are lowered. Secondly, changing climate results in more extreme weather, including droughts, hurricanes, extreme rainfall etc. Total yields are obviously reduced under those circumstances too. (Alt citation, PDF)

This was recently brought home to me by an Australian cousin, who laments the drought his country has been going through for some time: he tells of kids in some parts of the country now entering high school, who have never seen rain.

Factor number four is the number of lunatic politicians, in their bid to never offend anyone while running for office, avoid telling the truth about ethanol from corn: it's doubtful it actually produces any additional (net) energy after it's energy inputs are calculated, AND it's going to (in fact, already has) further increased food costs.

I watched a shameful 20/20 series where every single presidential candidate at a town-hall type meeting claimed that ethanol was part of the solution, rather than more likely to contribute to an even bigger problem. Whatever happened to a "give 'em hell", Harry Truman style candidate? Are they all too meek, too bland, and too gutless for even one of them to stand up and tell the truth? And the truth is, is that ethanol, bio-diesel, or any other fuel made from food sources is only going to add to food inflation, possibly to serious food inflation.

One article also discusses many of these issues and interestingly points out that China, to feed itself, should be adding a quantity of arable land equal to Maine, every year. Instead, it has lost that amount every year over the past decade. Another article, in the respected Popular Science magazine, discusses these looming food questions.

There are, of course, always those head cases who are convinced that technology will solve any problem. However, increasing technological solutions have coincided with increased energy demands and, in a global warming world, one of these trends most likely has to give.

I read a recent article suggesting that food skyscrapers may be the way of the future - but these won't be coming any time soon and, due to costs, may end up with all those other strange Popular Science ideas that never see the light of day due to cost or technical issues that can't reasonably be overcome.

The Confused Capitalist will provide some practical and investment advice on how to deal with this over the coming while.

More reading sources:


JW

The Confused Capitalist

Sunday, June 17, 2007

Beating the S&P 500

Back in early 2006, The Confused Capitalist suggested a low maintenance model portfolio that I felt would outperform the S&P500 over the next five years or so. The portfolio was based on certain themes, some of which are ones which have generally proven to outperform over longer periods of time, such as buying value positions and small companies.

Additionally, I felt that commodities and emerging markets would continue to benefit from the world situation, and that the US dollar would continue to be under pressure - thereby adding to investments denominated in something other than US$. I suggested positions in a total of six ETFs, at values of 7.5% to 25% of the portfolio, with most around the 20% range.

To compare, we suggested a suitable tracking comparison would be the S&P500, as represented by the "SPY" ETF which was then priced at $131.47. It closed Friday June 15, 2007 at $153.07, a gain of 16.4%, which is pretty good. Add in dividends of roughly 2% or so, and the total gain is about 18.4%. If you'd gotten this, you would have beaten about 80% of the mutual funds out there, using traditional five year horizons as a guide (only 1 in 5 mutual funds beats the index, when the period is five years or so).

Sidebar note: If you're on a blog aggregator, you can visit The Confused Capitalist here (or here: http://confusedcapitalist.blogspot.com/) for additional articles and exclusive content!

Let's see how our own simple ETF-based portfolio, which looks like this, performed:

  • 20% weighting to a broad-based international ETF - EFV - $64.91 - ishares product tracks the MSCI EAFE Value Index, which tracks European, Australian, and Far Eastern markets. This ETF closed at $78.92 on Friday June 15, 2007, for a 21.6% gain, plus dividends. Advantage: The Confused Capitalist.

  • 20% weighting to small company - IWN - $74.99 - ishares product tracks the Russell 2000 Value Index (US small cap). This ETF closed at $85.11 on Friday June 15, 2007, for a 13.5% gain, plus dividends. Advantage: The S&P500.

  • 25% weighting to emerging markets - EEM - $105.45 - a broadly-based (for emerging markets) ishares product tracks the MSCI Emerging Markets Index. This ETF closed at $132.42 on Friday June 15, 2007, for a 25.6% gain, plus dividends. Advantage: The Confused Capitalist.

  • 20% weighting to the value portion of the S&P 500 - IVE - $70.62 - an ishares product tracking the value portion of the S&P500. This ETF closed at $83.78 on Friday June 15, 2007, for an 18.6% gain, plus dividends. Advantage: The Confused Capitalist.

  • 15% Own Ideas (in this case, my belief that commodity-oriented countries will do well for the next five to ten years). I'd equally weight a Canadian ETF (EWC) - $24.86 - and a Brazilian ETF (EWZ) - $44.25. The EWC closed at $30.58, for a 23.0% gain, while the EWZ closed at $62.66, for a 41.6% gain. Advantage both: The Confused Capitalist.

These weightings result in a total gain of 22.0%, plus dividends which, in this case, would add about another 1.5%, so the total would be about 23.5%, versus the 18.4% all in of the SPY ETF.

So not only did the Confused Capitalist beat the S&P500 ETF by five percentage points in just over a year, it did so in 5 of the 6 ETFs selected, showing broadly-based outperformance. The Confused Capitalist feels comfortable continuing to hold these same positions and original weightings going forward over the next year or so, and will check back in 2008 to compare relative performance.

I hope to continue to show that a low-maintenance portfolio, with modest thought given to what the future might look like, will continue to be able to outperform static indices. Those wishing to view some similar simple portfolios felt to have an excellent change to outperform the S&P500, should go here, here and here.

With these increases in value, the weightings have changed slightly going forward, but not enough to warrant a re-balancing. These weightings are now:
  • EFV - 20.0%
  • IWN - 18.6%
  • EEM - 25.7%
  • IVE - 19.4%
  • EWC - 7.6%
  • EWZ - 8.7%
June 18 2007. 12:10PM Pacific time. Correction made to the EEM discussion bullet, which misstated (understated) the current price and percentage increase. Ah, the dangers of using the "cut and paste" function!


JW

The Confused Capitalist

    Saturday, May 05, 2007

    Next Fed Move will be up, not down! Inflation not quelled yet.

    After an extended break to see my brother get married in Los Angeles, including a visit down to Sea World and Disneyland, some time away for training, and just a general break, the Confused Capitalist is back.

    Note: If you're on a blog aggregator, you can visit The Confused Capitalist here for additional articles and exclusive content!

    The Confused Capitalist has been busy reading the tea leaves, as well as a very interesting book on the process of "intuitive" thinking, and in the Blink of an eye, realized that the Fed will have to move interest rates up, rather than down.

    Inflation is not yet quashed, and inflation around the world also appears to be moving towards the upside. A declining US currency won't help things either, as inflation will be "imported" in addition to domestic pressures. The Fed will most likely begin to move rates up in nine to 15 months, and it won't just be 25 basis points until they stop. Where they will stop, I'm not certain, but it will be at least 50 basis before they pause again, but possibly as high as 200 basis points, looking out over the next 24-36 months.

    Well, that's my tea leaves reading for this quarter. These days sure feel like the 1970s in many ways.


    JW

    The Confused Capitalist

    Monday, April 09, 2007

    Book Review: The Sleuth Investor by Avner Mandelman

    This is a book which every serious investor must acquire. A book which can help level the field between the large institutional investor, with all the attendant advantages, and the small investor like me.

    While I own some 25+ investment books, including classics such as "Security Analysis", "One Up On Wall Street", and "Common Stocks and Uncommon Profits", I have to say that I think this book will prove to be the most personally enriching.

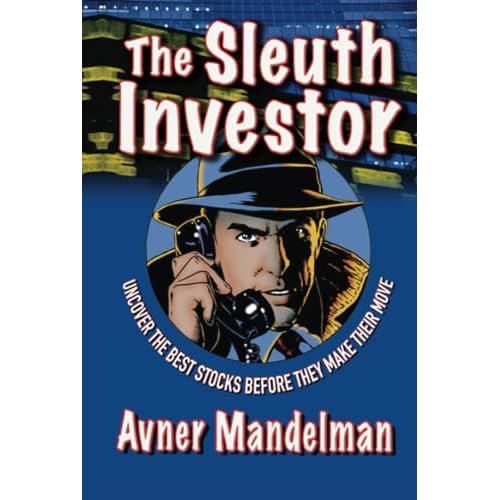
    I could just tell right from the cover that this book, The Sleuth Investor, was going to be different from almost every investment book I've every read. Instead of a picture of Bulls or Bears, The Author, Dollars Floating in the Sky, or a Stock Exchange Building, instead there's a picture of what appears to be a private detective or, perhaps, a field operative. As I surmised from the cover, the book didn't disappoint.

    And the dust cover picture cuts to the heart of the difference between this book and all the other investments books I've read. The difference between receiving second hand, "academic" information of stocks (eg annual and quarterly reports, etc.) or gathering that publicly available information, PLUS quality information directly from the field.

    Note: If you're on a blog aggregator, you can visit the Confused Capitalist here for additional articles and exclusive content!

    The author, Avner Mandelman, president and CEO of investment firm Giraffe Capital, tells you exactly how to sleuth out investment opportunities "in the field". He gives direct examples of what, who, how and when. This is not a book full of numbers and ratios; Mr. Mandelman knows full well that the investment world is full of these, yet the number of investors able to outperform the market is very few indeed.

    In this book, he shows you how to both lower your investment risk profile, all the while increasing your odds of batting not just one, but numerous, investment home runs. While some investing books, such as Ken Fisher's "The Only Three Questions That Count: Investing by Knowing What Others Don't" state the importance of acquiring exclusive or near exclusive information, his book doesn't actually show you how to achieve that, since it only provides some further academic tools to suggest whether you might know something others might not know. On the other hand, if you apply Mr. Mandelman's suggested techniques, you'll know when you know something others don't when you are finished "sleuthing" a stock story.

    I certainly haven't read any like it before, although there's hints of "One Up On Wall Street", by Peter Lynch here and there, and some visible heritage to "Common Stocks and Uncommon Profits", by Phillip A. Fisher. There's also some obvious lineage to Warren Buffett's ideas as well.

    The book is a great read as well; it was the first investment book I've read since "On Up On Wall Street" by Peter Lynch that I when read it in bed, it was because it was so interesting, rather than because I intended as use it as a non-prescription sleep aid.

    Canadian readers who've followed the business community here for a dozen years or so, will also especially savour a couple of the tales of "investment sleuths" from a couple of the high profile business stories and people here.

    In one example, the "Z-Plat" story (almost certainly the Bre-X fraud) a sleuthing pension-fund manager saved his company a small fortune from physical sleuthing of a mining company's claim, and later turned that same information into a small personal fortune.

    In another story, "Chipperware", Mr. Mandelman explains how he was able to turn a tidbit of public information about a piece of a one-of-a-kind designer clothing into a small fortune. One never knows of course, but many of the facts here appear to parallel some known public information about the wife of Corel Corporation's founder (Dr. Michael Cowpland), the flamboyant Marlene Cowpland, and an extremely expensive dress she wore to a gala.

    Yes, as you read the stories of "Chipperware" and Z-Plat, be aware that these tales are almost certainly real business events as well.

    In summary, this is an investment book that meets its dust cover promises. I cannot stress highly enough the importance of making this soon-to-be investment classic part of your permanent investment library.


    JW

    The Confused Capitalist

    Curious Capitalist? Non! Canadian Capitalist? Non!

    Did you take a wrong turn? An internet storm wash to the wrong shores?

    Just in case you arrived here looking for the Curious Capitalist, he's not here! He - Justin Fox of Time magazine - joined the blogosphere many, many, months after I did. An interesting read from time to time. Here's his inaugural blog posting.

    Note: If you're on a blog aggregator, you can visit The Confused Capitalist here for additional articles and exclusive content!

    Nor am I the Canadian Capitalist, who was here, but is now here. He appears to have been blogging since late 2004, about a year and a half earlier than me.

    No, if you're here, you've arrived at the Confused Capitalist. Feel free to poke around the site, and let me know if you particularly enjoyed something, or were particularly annoyed by something.


    JW

    The Confused Capitalist

    Friday, April 06, 2007

    $124.93! Thank you!

    I received my first cheque from Google for the ads running with my blog. Of course it's primarily based on volume of click throughs.

    After 180 articles, and hundreds of hours spent maintaining and researching articles that ended up in this blog, I got my cheque of $124.93. Which ain't bad for a hobby I'd do for free; lucrative it's not, but it's nice to be able to take the Mrs. Confused Capitalist out for a nice dinner (or, as she's want to do, pay a couple of bills with it).

    Note: If you're on a blog aggregator, you can visit The Confused Capitalist here for additional articles and exclusive content!

    Luckily, I received a speeding ticket lately that'll nicely gobble up that cheque. The ticket cost? $124 even. Which leaves me trying to figure out what to do with the 93 cents.

    In any case, thanks to my readers, and thanks for those who click through once in a while!

    Oh, by the way, I recently received a copy of the newly-minted book "The Sleuth Investor" by the excellent Avner Mandelman. I am enjoying the book immensely and will provide a review of it very soon. It reads very well and provides considerable investing insight.


    JW

    The Confused Capitalist

    Thursday, March 29, 2007

    Are Growth Stock Prices Reflecting a Cheery Consensus?

    In one of his chairman's letters, Warren Buffett once stated that ...

    "The future is never clear, you pay a very high price in the stock market for a cheery consensus."

    I just looked at the 10 year returns of the Russell 1000 Value Index, and the Russell 1000 Growth Index.

    Frightening, the cost of a cheery consensus, particularly those orienting towards the growth side of the equation.

    Sidebar note: If you're on a blog aggregator, you can visit The Confused Capitalist here for additional articles and exclusive content!

    The difference in the current valuation metrics on the two indices are significant, scary, and points to, may I suggest, more of the same looking forward.


    JW

    The Confused Capitalist

    Thursday, March 22, 2007

    A superior index arises: just a better mousetrap

    This can either be read as a stand-alone posting relating to why fundamental indexing is a better way to go than tracking a conventional index, or it can also be read as part two of two of a book review of "The Little Book of Common Sense Investing", by John Bogle.

    As relayed in part one of my review, I found the evidence presented by Mr. Bogle to be almost overwhelming that investing in a low-cost index fund was virtually the only way for the average equity investor to outperform the broad market, like the S&P 500, over time. A very good method as the book clearly details.

    However, in the book (chapters 12, 14, 15 and 16), Mr. Bogle suggests that some of the new fundamental indices (e.g. FTSE RAFI) aren't going to stand up to the test of time, as market capitalization-weighted indices (such as the S&P 500) have. He intimates that, having seen various "better mousetraps" come and go, so too will fundamental indexing (which back-testing shows has outperformed a cap-weighted by nearly 2% annually, a huge margin). This is essentially, he claims, just another method to part the foolish from their prospect of future returns.

    He denigrates the back-testing of these fundamental indices as if that was somehow undesirable. I personally fail to see the difference between the back-testing done there, and Mr. Bogle's own back-testing that led him to the conclusion that low-cost index investing was going to beat the then conventional mutual fund of the day (an advantage that has continued to hold up to this day).

    Mr. Bogle fairly asks the question of why these fundamental factors (fundamental factors are centered on accounting items, like book value, dividends paid [or dividend growth rates], earnings, revenues, etc.) have not been properly exploited by stock markets in the past? While there have been tons of academic studies pointing out that a stock-picking method using virtually any of the aforementioned factors as a major stock-picking factor would have outperformed the broader market, that still doesn't really answer the question.

    The question is best answered by examining behavioural research. In other words, it has to do with the emotional nature of people, something that even mutual fund managers are subject to, as clearly evidenced by the typical 100% turnover on the conventional mutual fund. Certainly, they also appear to be "taken in" by a "good story", as much as anyone. For more insight on this issue, see the following (warning: large pdf file) commentary, Seven Sins of Fund Management. In short, the problem is, my dear Mr. Bogle, interference from human beings.

    Just as Mr. Bogle was then a pioneer of the day, by exploiting something seemingly obvious and mundane (i.e. 1. costs matter and 2. don't get trapped by "the story") it seems hard to believe that no one can build a method for a relatively sustainable advantage over a conventional index. In the future, the building of these fundamental indices today will probably be seen as something that should have occurred much earlier, given their obvious superiority.

    But getting back to the business at hand, if, as alleged by Mr. Bogle early in the book, that long-term investment returns more or less parallel the returns of the stock market of the underlying businesses, doesn't it make sense to construct an index which actually gives weighting to those factors, as opposed to the more temporary and whimsical valuations imposed by market activity?

    Doesn't it make sense to try and limit or exclude the "speculative" return (positive and negative) he discusses, which is, essentially, the contribution (deduction) to (from) short-term returns from stocks becoming over (under) priced? Fundamental indices attempt to do that: exclude the most-egregiously over-priced stocks, by fundamentally examining the books of each company. Conversely, these indices also include more of the relatively undervalued companies. That these indices might succeed over the longer-term would be due to the rules-based inclusion of companies into the index. A fairly simple, but effective, way of eliminating or minimizing poor investment decisions: rules!

    After a time, I think Vanguard, Bogle, and other indexers will recognize that these are superior indices. Then, more index funds will be created to track them. Because the basis of inclusion into these indices are the actual economic activity of the companies themselves, rather than the more capricious valuations assigned by the market activity of the moment, they can finally answer a question Bogle poses in the book: How to know which companies are over-valued in a conventional index? Effectively, the books of the companies themselves answer that question.

    In the end, an index that examines the fundamentals of companies in some manner simply has to be better than one which only considers the temporary selling prices of their stocks. Vanguard and others will finally realize this, and bring the same ruthlessness to cutting costs that they did to tracking the S&P 500, for instance.

    Whether these indices will continue to significantly outperform conventional capitalization-weighted indices starting twenty years from now, the answer is "probably far less" than current back-testing has shown was available. As the "rise of the machine" eliminates emotional interference (1, 2) from making "on mass" good investing decisions, these market inefficiencies will be exploited such that they will disappear over time. And while the costs are currently slightly higher for these ETFs (about 0.5% annually) than an extreme low-cost conventional index-tracker (about 0.19%), the cost/benefit equation seems to be worth it (i.e. you pay an extra 0.3% or so, to get about 2% more).

    In the interim though, as these inefficiencies are finally properly captured over the next decade or two, it's possible that excess returns will even exceed that shown in back-testing. And any advantage that is likely to persist over ten to twenty years isn't something to be ignored, in my view.

    Anyone with a broadband connection and who wants to really understand the multitude of reasons why these are superior indexes, are suggested to go to these two (one, two) video presentations, by Rob Arnett of Research Affiliates.


    JW

    The Confused Capitalist
    Monday, March 19, 2007

    Editorial: Why a Responsible Fed Won't Lower Rates Anytime Soon.

    Notwithstanding the perceived subprime "crisis", a responsible Fed can't lower rates anytime soon. Why?

    Because the consumer is finally being told, in no uncertain terms, to smarten up, stop spending more money than you have, and save a little bit. With this message, (and a puncturing of the home-ATM cash-machine) inflation will finally begin to get tamed.

    Any loosening of the money supply at this point, while mitigating the short-term damage that will soon become evident in bloated housing markets, will only move that day of reckoning into the future. A future time which which would then have bleaker, more uncertain and more unstable fundamentals, from which to try making essentially the same maneuver.

    No, dear readers, this is the medicine that great-great-grandmother used to force down great-grandmother's throat: a nasty-smelling, foul-tasting, herbal concoction that nearly gagged the dear girl. But medicine that helped the patient recover sooner, and more robustly.

    To lower interest rates at this time is the equivalent of turning up the heat in the house, so that the feverish patient may feel comfortable. Foolish. Understandable to some, with the child whining so loudly but, all the same, foolish.

    And a responsible Fed just won't do that.


    JW

    The Confused Capitalist

    Saturday, March 17, 2007

    S&P 500 Future Returns

    Readers may wish to take the investment poll located on the right hand side of the blog which asks what you expect the S&P 500 rate of return to be over the next 10 years.

    Thanks to Geoff Gannon of Gannon on Investing for providing this poll.

    JW
    The Confused Capitalist

    The Little Book of Common Sense Investing - Book Review

    Subtitled: The Only Way to Guarantee Your Fair Share of Stock Market Returns.

    For those equity investors that read the compelling message provided by this book and follow author John Bogle's advice, the book might have several other compelling subtitles, such as "Relentless arithmetic proves it's almost impossible to outperform a low-cost index fund", or "Equity investors: find a less expensive/more profitable hobby! Like investing in a low-cost index fund!", or, more simply, "Most mutual funds suck!".

    This book, by the father of the index-investing movement and founder and former head of the Vanguard Group uses "relentless arithmetic" to prove exactly why individual investors will, as an average, dramatically underperform the market averages (about 9.5% annually over long periods of time, according to the book). Bogle has been a persistent critic of traditional mutual funds, which have an excessive average cost of 2.5% annually, compared, for instance, to the Vanguard index fund cost of just 0.19%. Bogle has been a critic because, despite the high cost of a conventional mutual fund, it doesn't, on average, outperform a low-cost index fund.

    Just considering the mutual fund cost portion of the drag (about 2.5% annually), this book shows that, compared to investing in the index, after 30 years, the typical mutual fund equity investor will only get about 50% of the market advance. After 50 years, this will decline even further, to only 31% of the total advance.

    These dismal averages don't even consider the propensity of investors to trade in and out various funds, ETFs, or stocks (transactional costs), nor the further drag of picking the wrong funds. These are significant sources of further underperformance.

    Bogle punctuates this message by regularly providing quotes from famous value investors and business school professors, to further support low-cost index investing. In some ways, I felt like the book was a form of Chinese water torture: at the end, it was all but impossible to dismiss its message. And that message is that low-cost index-fund investing is the "only way" to get your fair share of market returns. As the book puts it, "by aiming for the average, you can beat the average".

    In summary, the book shows the three sources of underperformance - which are very significant in their totality - which is likely for average equity investors:
    1. Excessive costs of conventional mutual funds;
    2. Transactional or trading costs as investors trade in and out of various funds/stocks etc. and;
    3. The costs of picking the wrong funds (investor pile into funds which have risen lately, and history shows most of these are poised for a period of underperformance; and visa-versa).
    Overall, this is a great book with a fabulous message for most investors, and most investors couldn't do wrong by following the approach espoused here.

    In a separate future posting, I am, however, going to take on one of Mr. Bogle's final messages: that some of the new products and new market indices aren't likely to provide superior returns any better than tracking conventional market capitalization-weighted indices (S&P 500 is one such index, and most widely-quoted indices are of this type). I believe this to be false, and hope to explain why I think so, using mostly Mr. Bogle's own words to explain why.

    No matter this relatively small dispute, I recommend that all investors unfamiliar with the huge advantages of low-cost index investing buy and read this book.


    JW

    The Confused Capitalist

    Sunday, March 11, 2007

    Profit from "U"

    I recently received two books: review copies from the well-known and respected John Wiley and Sons, publishers of many, many, business and investment titles. These two books are entitled, "Profit from China" and, "Profit from Uranium" and are printed under Wily's imprint "Investment U". Each is priced at $29.95 ($US) or $35.99 ($Cdn).

    These "books" are total less than 50 pages in length and are written in the style of a friend-to-friend informal report. The actual number of pages discussing the topic at hand is less than 25 pages. That's right, the books are effectively priced at more than a $1 per page.

    Each of these books provides a little bit of background around each investment theme and then suggests four stocks or ETFs that could benefit from continued investment into each respective theme.

    I have to say that I agree with the review of these books given by portfolio manager and fellow blogger Roger Nusbaum.

    While the "books" have some utility I have to say that I'm left with the impression that Wiley is viewing these as a potential "profit center" - meaning they view you, dear reader, as their profit center in this case. I think that Wiley can do a lot better than titles like these - or alternatively, reduce the price to something commensurate with the effort ($3.99?) or effective utility ($5.99?). I think the unfortunate result of publications like these will be to cheapen the name and reputation of Wiley as a publisher of quality business titles.

    But that's just my opinion. You are, of course, free to form your own. For only $29.95.


    JW

    The Confused Capitalist

    Monday, March 05, 2007

    Thinking About ETFs

    As many readers here are aware, I'm a pretty big fan of ETFs, particularly as a solid foundation for a portfolio. However, I think that you have to drill down into the particular ETFs to consider what their chances of outperformance are.

    Obviously, buying ETFs that have constituent companies with a high return on capital (or equity) and a low price (as in a low PE ratio), are likely to return greater capital to your wallet over the long term. That's why I try to drill down into these ETFs before I personally buy them.

    One research firm that does this for you is AIR AltaVista Independent Research Inc. Its' methodology was recently highlighted in an interview with AltaVista Research President Mr. Michael Krause, by fellow blogger (here) James Picerno.

    One thing that definitely caught my attention was ... statement in the later part of the interview relating to fundamentally-indexed ETFs ...
    I am quite a fan of fundamental indexing. We’re getting new flavors and gimmicks in indexing all the time, but I think fundamental indexing is one of the most genuine and promising developments in a long time.

    I have blown this horn fairly often in the past ... they appear to simply be a better way to invest. But whether you choose these fundamentally-indexed ETFs, or one of the many ETF allocations which still aren't fundamentally indexed, then researching your choices in relation to price and value measures is almost certain to improve your investing outcomes.


    JW

    The Confused Capitalist

    Tuesday, February 27, 2007

    Happy Birthday to me ... to me .... to me ....

    Just like an unruly child, the Confused Capitalist has passed his first birthday on this earthly plane (... this blog was started February 18 2006), with a happy smile on his face.

    Hopefully, I've written something a little bit different from everybody else and something that others have found worthwhile; I've generally had fun doing this. A promotion in the latter part of last year kept me busier than usual, hence the relatively infrequent blogging over the past six months.

    However, as the Confused Capitalist enjoys writing both as a means to learn, self-inform, and teach others, I will be launching an environmental/global warming blog later this year. I hope some of you might wander over there when this is launched for some ideas, insight and discussion as we move towards a sustainable future, before all the natural systems begin completely failing.

    In the meantime ... happy birthday to me ... happy birthday to me ... to me ... :-)


    JW

    The Confused Capitalist

    Saturday, February 17, 2007

    How Low Can You Get? Extremely Low PEs Crush Market Averages

    A series of stories on extreme low PEs is interesting in that it shows two things:

    Firstly, that the "Rise of The Machine" has value for investing purposes (i.e. automatic selection without further human intervention, once the investment criteria rules are written).

    This is currently being exploited through many semi-active and enhanced ETFs, like the Power Shares, Wisdom Tree and Claymore Investment types, and through "value screen" investing.

    The second interesting thing is that extreme value situations crush market averages.

    Here are the stories of John Dorfman's extreme value investing via his "Robot Portfolio":

    2006 Portfolio
    2005 Portfolio
    2004 Portfolio
    2003 Portfolio
    2007 Canadian Version

    I hope these stories prove useful to you.

    JW

    The Confused Capitalist

    Sunday, February 11, 2007

    The Only Three Questions That Count

    This is part 2 of 2, relating to a review of Mr. Fisher's book. The first segment is here.

    I have some issues with Mr. Fisher's book and some of his "revolutionary" thinking. Given the tone of his book, I'm certain he would be absolutely dismissive of what I have to say but, nevertheless, I'm going to charge in anyway.

    Mr. Fisher's big opening statement in his book challenges a long-held market axiom that high PE's denote reduced returns for some period of time into the future. He states that the year immediately following a high PE year has virtually no statistical inverse correlation. While this might be true, it ignores the fact that there is heightened risk of a reduced return into the relatively near term future. Whether that lower return is realized in the immediate year following, Mr. Fisher's data suggests, no.

    However, an investor (rather than a "speculator" or "trader") would be foolish to ignore the reduced odds of outperformance that this period provides. For some further information and a detailed study on this issue, please go over to this Gannon On Investing series, which discusses this in greater detail. (Use the top navigation link to continue moving forward in this interesting series). Essentially, Mr. Gannon's work shows that poor returns (perhaps not the immediate year following) generally follow high PE years.

    I find that his presentation and discussion of the data is of considerably more value to me than Mr. Fisher's more short-term consideration. In terms of data presentation, in Mr. Fisher's book, in an attempt to convince that there's virtually no correlation between PEs and market returns, he presents what he calls a "Bell Curve" showing relative PEs. Here is a truncated version of his "Bell Curve":

    (see Figure 1.3 on page 18 of the book).

    When I look at this, it doesn't remind me of a Bell Curve, which I always understood to look something like this ...

    ... so when I look at it, my mind still tries to fit a rough bell curve to it. What I can clearly see is that, on the periphery, there appears to be a clear correlation between average returns and PEs. For instance, the average return from the 11 occurrences in the far left hand (low PEs) column is 20.0%. If I aggregate all the small right hand columns (High PEs), this totals some 17 occurrences, and the average return there is just 6.5%.

    Perhaps a better way to think about this, I arrive at, is that in the middle values, the PE isn't the most important determinant of future return. But on the edges, it's clearly very important. Geoff Gannon's work certainly supports this thesis too. But I know that Mr. Fisher would probably be completely dismissive of me, attributing my criticisms to my inability to ditch an old world view.

    Later in the book, he puts to rest another worry, that high government deficits and debt result in poor market returns. Don't Worry!, his research shows, Be Happy! I'd say that the way he approaches this theme is similar to the first; he takes the short term view and therefore "proves" this doesn't impact the market.

    I look at it like this: while the party is going on with borrowed money, all looks great. There's no evidence to suggest that the house will be trashed the next morning and in dire need of repair. Party on dudes!

    However, over the longer term, a sensible brain would say that the money is going to have to be paid back, and given the the US already has one of the lower tax regimes in the developed world (suggesting that the opportunity for service cuts are somewhat limited), how will this money likely be paid back? Hummm, by raising taxes, perhaps even corporate taxes?? And when taxes are raised, what is that likely to do to corporate profits, or at least profit growth rates?

    In summary, I find that Mr. Fisher often takes a relatively short term view in framing his questions, more akin, in my view, to a trader, than a long-term investor. Having said that however, and despite my criticisms here, I still think that the book is a worthwhile read.

    Just be careful how you use the outcome of some of the questions that Mr. Fisher frames.

    Feb 13/07: I have added this post-script because I think I have probably been somewhat harsh in my criticism of this book. What makes it worthwhile, in my opinion, is that it's one of the very few books out there that shows how a "top-down" approach might succeed.

    Most books - mine included - tend to focus on "bottom-up" approaches that focus on relative and absolute valuations. Some wander off into the "asset-allocator" field as a sideline, but few provide any indication of how a top-down approach might be successfully employed and some tools to do that with. Mr. Fisher's book does that.

    However, I'd still be cautious as to using the exact answers that Mr. Fisher comes up via his own questions, as I believe there's an inherent amount of risk in ignoring certain longer-term probabilities [something I think that many of Mr. Fisher's questions do] - i.e. poorer longer term returns when investing when PEs are high; and government deficit and debt situations that may act as trigger events for market debacles.


    JW

    The Confused Capitalist
    Saturday, February 10, 2007

    Investment Cycle clock

    I thought that this graphic, by Merrill Lynch, was worth looking at in terms of where they see the economy in the cycle, and the type of investments they generally see as outperforming during any particular part of the cycle.

    The other thing I thought I might try taking a stab at is how long each portion of the cycle typically lasts. Based only on my observation over time, I might suggest that the cycle has roughly 3,4,2,1 counts. My (un)educated guess is that the recovery portion usually is 3 helpings of time, the boom is 4 portions of time, the slowdown is 2 portions and the recession is 1 portion of time.

    Using something like this clock may help you to time your type of investments a little better.

    Hat tip to the Big Picture for this worthwhile graphic and also to his continuing coverage of the housing situation. Unlike many analysts, Barry Ritholtz has figured out where that particular train is headed (and it's not to the "Happy Days Are Here Again" station, just yet).


    JW

    The Confused Capitalist

    Sunday, January 28, 2007

    Book Review: The Only Three Questions That Count, by Ken Fisher

    Ken Fisher is one of the richest men in America and is a renowned investment manager, following in the footsteps of his - also famous - investor father, Philip Fisher. Each approaches/ed investing with different styles on how to make money.

    Philip was a proponent of a concentrated basket of stocks, chosen in relatively few sectors in which one might gather some deeper knowledge over time, and in which relatively exclusive and important information ("scuttlebutt") might be known.

    Ken Fisher, the author of this book, on the other hand is more of a top-down, "value-screen" guy, who recommends staying relatively close, asset-class percentage-wise, to a broad-based benchmark. He also recommends a broad portfolio of about 50 stocks. Despite the obvious differences in styles, each style has proven to be successful, respectively, for father and son, and for those who follow. But success only happens for those followers who are willing and able to ask the suitable questions needed to succeed for each investment style.

    Ken's style revolves around asking the following three questions:
    (1) What do you believe that is actually false?
    (2) How can I fathom what others find unfathomable?
    (3) What the heck is my brain doing to blindside me now?

    Asking the first question calls on you to challenge yourself to find or analyze data to show what you believe is actually false. By uncovering this, we can invest in a different way than we had previously, and in a a different way that many people believe to be true (which is actually false), and, thus, swimming before approaching tide is seen by all, succeed in outperforming the crowd. Catching the early rise of the wave, if you will. Using this question, Ken purports to show that investing when price-earnings ratios (PEs) are high isn't a sign of poor returns to come. This is his big signature statement that challenges a long-held market axiom. More on this in another posting to follow.

    The second question calls on you to look for relationships where some (sensible) economic theory can explain what might occur in the future, based on demonstrated relationship to something else that has proven to have some predictive power (correlation). The question can also be stated as "What causes X?".

    The final question relates to considering how various behavioural cognitive reasoning flaws might be sabotaging your success as an investor. I have written about many of these factors on my blog before, and these are often highlighted at Abnormal Returns or CXO Advisory, and it's nice to see that the importance of these are becoming more widely written about.

    In general, I found the book to be worthwhile, filled with lots of practical tips and thoughts; and the application of the questions cannot but help make you a better, more astute investor over time.

    However, I have two issues with the book:

    Firstly, I find that Mr. Fisher is very condescending or even downright insulting to some specific people, or classes of people - based on their chosen profession. I find the first to be juvenile and needlessly insulting, while in the second instance he engages in negatively stereotyping a "class" of people, an attribute I frankly have some trouble understanding in a person of his obvious intelligence. In this regard, I think Mr. Fisher should try to display a little more maturity, and tact. As you can probably tell, this behaviour irritated me to a considerable degree.

    Secondly, I have some issues with Mr. Fisher purporting to show that high PEs don't denote high market risk. My problem with the posing of his question, rationale and presentation of the "facts" in relation to this will be discussed in a future posting.

    Until then, stay safe and use the three questions to consider the investment world in general, and the questions answered in Mr. Fisher's book in particular.


    JW

    The Confused Capitalist

    Sunday, January 21, 2007

    The value of doing nothing ...

    Left: Superior investor Rip Van Winkle.

    According to a recent news item by investment newsletter tracker Mark Hulbert, results from tracking both investment newsletter writers, professional mutual fund managers and even individual investors, results attained by measuring the performance of "last year's portfolio" is better, on average, than the results of the current portfolio.

    In the newsletter example given, "yesterdays" portfolio beat the current one by, on average, 80 basis points. This is outperformance - measured against one's own investing skills - which is not to be sneered at.

    As Hulbert put it, the logical conclusion to arrive at in portfolio changes then becomes ...
    ... what these results do suggest is that we should place a large burden of proof on making a change in our portfolios. Unless the arguments in favor of such a change are particularly compelling, we probably should simply do nothing.

    Doing nothing, however, is harder work than most investors want to subject themselves to.


    JW

    The Confused Capitalist

    Saturday, January 13, 2007

    Ticker Sense Poll Participant

    The Confused Capitalist has been thinking about its weekly participation in Birinyi Associates Ticker Sense's "Weekly Blogger Sentiment Poll". The poll asks the question ... "What is your outlook on the US stock market for the next 30 days?"

    After some consideration, The Confused Capitalist will no longer be participating in this poll. Unfortunately, the time frame asked about is too short to measure anything but, essentially, the sentiment of the moment, rather than speaking to longer term trends and relative valuation levels.

    Market movement over such short periods of time are almost solely based on emotion, random occurrences, or virtually unforeseeable events. While I admire the attempt to do something different from others (such as this poll), I have to weigh that against suggesting that investment bloggers - who have many neophyte investors as readers - are able to divine market trends over such a short period of time.

    If the question was re-worked to indicate a longer time frame, such as forecasting a market outlook over the next 18 to 36 months, then The Confused Capitalist will duly reconsider its position (if so asked). However, I would also like to thank Birinyi Associates for the honor of being an inaugural participant in this poll.


    JW

    The Confused Capitalist